Autonomous Vehicle (AV) Edge Compute Rig Market Report 2026
Global Outlook – By Component (Hardware, Software, Services), By Deployment or Delivery Model (On-Vehicle, Near-Vehicle Edge, Cloud or Hybrid), By Application Type (Autonomous Vehicles, Advanced Driver-Assistance Systems (ADAS), Fleet Management and Logistics, In-Vehicle Infotainment or Connected Vehicle Services, Smart City Mobility or V2X Applications), By End-User or Client Size (Automotive Original Equipment Manufacturer (OEMs), Fleet Operators or Logistics, Public Sector, Technology Integrators and Tier-1 Suppliers, Aftermarket or Retrofit) – Market Size, Trends, Strategies, and Forecast to 2030
Autonomous Vehicle (AV) Edge Compute Rig Market Overview
• Autonomous Vehicle (AV) Edge Compute Rig market size has reached to $3.35 billion in 2025 • Expected to grow to $9.14 billion in 2030 at a compound annual growth rate (CAGR) of 22.2% • Growth Driver: Expansion Of 5G Networks Fueling The Growth Of The Market Due To Rising Need For Ultra-Fast Low-Latency Connectivity • Market Trend: • North America was the largest region in 2025 and Asia-Pacific is the fastest growing region.What Is Covered Under Autonomous Vehicle (AV) Edge Compute Rig Market?
An autonomous vehicle (AV) edge compute rig is a specialized hardware system designed to process and analyze data locally within a vehicle in real time. It enables high-speed computation for tasks such as perception, navigation, and decision-making without relying solely on cloud resources. By handling complex artificial intelligence (AI) workloads at the edge, it enhances the safety, efficiency, and responsiveness of autonomous driving systems. The main components of the autonomous vehicle (av) edge compute rig includes hardware, software, and services. Hardware refers to high-performance edge computing units installed in or near vehicles that process sensor data from cameras, LiDAR, radar, and other systems in real time to support autonomous driving and ADAS functions. There are deployment or delivery models such as on-vehicle, near-vehicle edge, and cloud or hybrid. The application types include autonomous vehicles, advanced driver-assistance systems (ADAS), fleet management and logistics, in-vehicle infotainment or connected vehicle services, and smart city mobility or V2X applications, and the key end-users include automotive original equipment manufacturers (OEMs), fleet operators or logistics providers, public sector organizations, technology integrators and Tier-1 suppliers, and aftermarket or retrofit providers.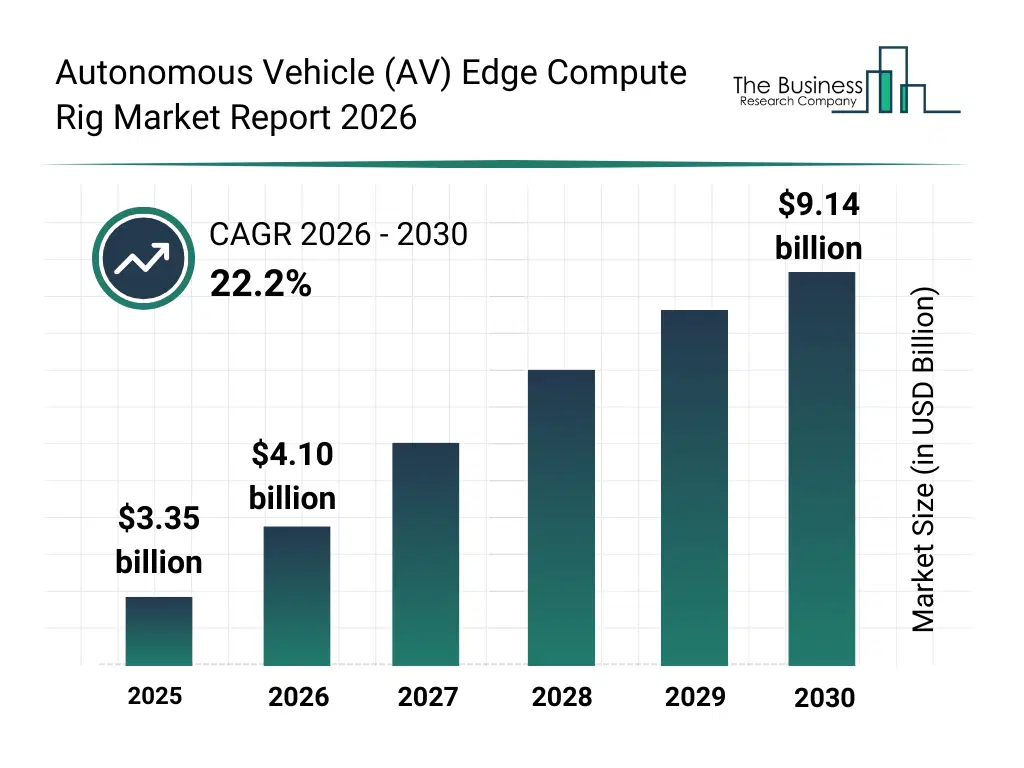
What Is The Autonomous Vehicle (AV) Edge Compute Rig Market Size and Share 2026?
The autonomous vehicle (AV) edge compute rig market size has grown exponentially in recent years. It will grow from $3.35 billion in 2025 to $4.10 billion in 2026 at a compound annual growth rate (CAGR) of 22.5%. The growth in the historic period can be attributed to increasing adoption of advanced driver-assistance systems, growing demand for real-time vehicle data processing, rising integration of artificial intelligence (AI) in automotive systems, expansion of connected vehicle deployments, and increasing use of high-performance sensors in prototype autonomous vehicles.What Is The Autonomous Vehicle (AV) Edge Compute Rig Market Growth Forecast?
The autonomous vehicle (AV) edge compute rig market size is expected to see exponential growth in the next few years. It will grow to $9.14 billion in 2030 at a compound annual growth rate (CAGR) of 22.2%. The growth in the forecast period can be attributed to growing need for low-latency edge computing in autonomous driving, increasing deployment of level 3–5 autonomous vehicles, rising demand for high-speed in-vehicle computation, expanding investments in mobility-as-a-service platforms, and growing integration of vehicle-to-everything (v2x) communication. Major trends in the forecast period include advancements in edge artificial intelligence (AI) accelerators, innovations in onboard compute architectures, developments in real-time sensor fusion technology, research and development in low-power artificial intelligence (AI) chips, and advancements in ruggedized automotive-grade compute hardware.
Global Autonomous Vehicle (AV) Edge Compute Rig Market Segmentation
1) By Component: Hardware, Software, Services 2) By Deployment or Delivery Model: On-Vehicle, Near-Vehicle Edge, Cloud or Hybrid 3) By Application Type: Autonomous Vehicles, Advanced Driver-Assistance Systems (ADAS), Fleet Management and Logistics, In-Vehicle Infotainment or Connected Vehicle Services, Smart City Mobility or V2X Applications 4) By End-User or Client Size: Automotive Original Equipment Manufacturer (OEMs), Fleet Operators or Logistics, Public Sector, Technology Integrators and Tier-1 Suppliers, Aftermarket or Retrofit Subsegments: 1) By Hardware: High-Performance Compute Units, Graphics Processing Boards, Central Processing Boards, Sensor Interface Modules, Vehicle-Grade Storage Systems 2) By Software: Edge Operating Systems, Real-Time Data Processing Platforms, Artificial Intelligence Inference Frameworks, Sensor Fusion Software, Cybersecurity Protection Software 3) By Services: Integration Services, Deployment Services, Maintenance Services, Remote Monitoring Services, Over-The-Air Update ServicesWhat Are The Drivers Of The Autonomous Vehicle (AV) Edge Compute Rig Market?
The expansion of 5G networks is expected to propel the growth of the autonomous vehicle (AV) edge compute rig market going forward. 5G networks refers to the number of global 5G connections, infrastructure deployments, and network coverage worldwide. The rise in demand for 5G networks is due to growing needs for ultra‑fast low‑latency connectivity that can simultaneously support billions of connected devices advanced mobile apps and data‑intensive services. Autonomous vehicle (AV) edge compute rig supports 5G expansion by providing the on board processing power and low latency computation needed for real-time autonomous vehicle operations that leverage 5G connectivity. For instance, in February 2024, according to the Global System for Mobile Communications Association (GSMA), a UK-based mobile industry association, 5G connections are projected to account for 51% of mobile connections by 2029 and 56% by 2030. Therefore, the expansion of 5G networks is driving the growth of the autonomous vehicle (AV) edge compute rig industry. The growth in electric vehicles is expected to propel the growth of the autonomous vehicle (AV) edge compute rig market going forward. Electric vehicles are automobiles that use one or more electric motors powered by rechargeable batteries or other onboard electrical energy storage systems instead of internal combustion engines. Electric vehicles are rising due to growing government regulations and incentives promoting low-emission transportation, which encourage manufacturers and consumers to shift away from fossil fuel–based vehicles to reduce carbon emissions and meet climate targets. Autonomous vehicle (AV) edge compute rigs benefit EVs by reducing energy consumption, as real-time, on-vehicle data processing minimizes reliance on power-intensive cloud communication, thereby extending driving range and improving overall energy efficiency. For instance, in May 2025, according to the International Energy Agency, a France-based government agency, global electric car sales exceeded 17 million units in 2024, reflecting growth of over 25%, with approximately 3.5 million more vehicles sold compared with the previous year. Therefore, the growth in electric vehicles is driving the growth of the autonomous vehicle (AV) edge compute rig industry. The rising adoption of cloud platforms is expected to propel the growth of the autonomous vehicle (AV) edge compute rig market going forward. Cloud platforms are centralized, internet-based computing environments that provide on-demand access to scalable infrastructure, software, data storage, and analytics for deploying and managing applications and services remotely. Cloud platforms are rising as they enable organizations to scale computing resources on demand without large upfront capital investment, allowing faster deployment, lower IT costs, and greater operational flexibility. Cloud-based platforms benefit autonomous vehicle (AV) edge compute rigs by enabling scalable model updates, as they allow centralized training, validation, and deployment of optimized AI models to edge hardware over the air, ensuring continuous performance improvement without increasing onboard compute load. For instance, in September 2025, according to Eurostat, a Luxembourg-based statistical office, 45% of businesses in the EU bought cloud computing services in 2023. Large businesses are more likely to opt for cloud solutions compared with SMEs. In 2023, 78% of large businesses bought cloud services, while SMEs bought 44%. Therefore, the rising adoption of cloud platforms is driving the growth of the autonomous vehicle (AV) edge compute rig industry.Key Players In The Global Autonomous Vehicle (AV) Edge Compute Rig Market
Major companies operating in the autonomous vehicle (av) edge compute rig market are Tesla Inc., Robert Bosch GmbH, NVIDIA Corporation, Continental AG, Qualcomm Incorporated, Advanced Micro Devices Inc. (AMD), Aptiv PLC, Texas Instruments Incorporated, Infineon Technologies AG, STMicroelectronics N.V., NXP Semiconductors N.V., Renesas Electronics Corporation, Microchip Technology Inc., ON Semiconductor Corporation, Lattice Semiconductor Corporation, ADLINK Technology Inc., Lanner Electronics Inc., AAEON Technology Inc., Horizon Robotics Inc., Vecow Co. Ltd.
This chart is for illustrative purposes; the full report includes a detailed competitor analysis and comprehensive overview of the top 10 companies in the market.
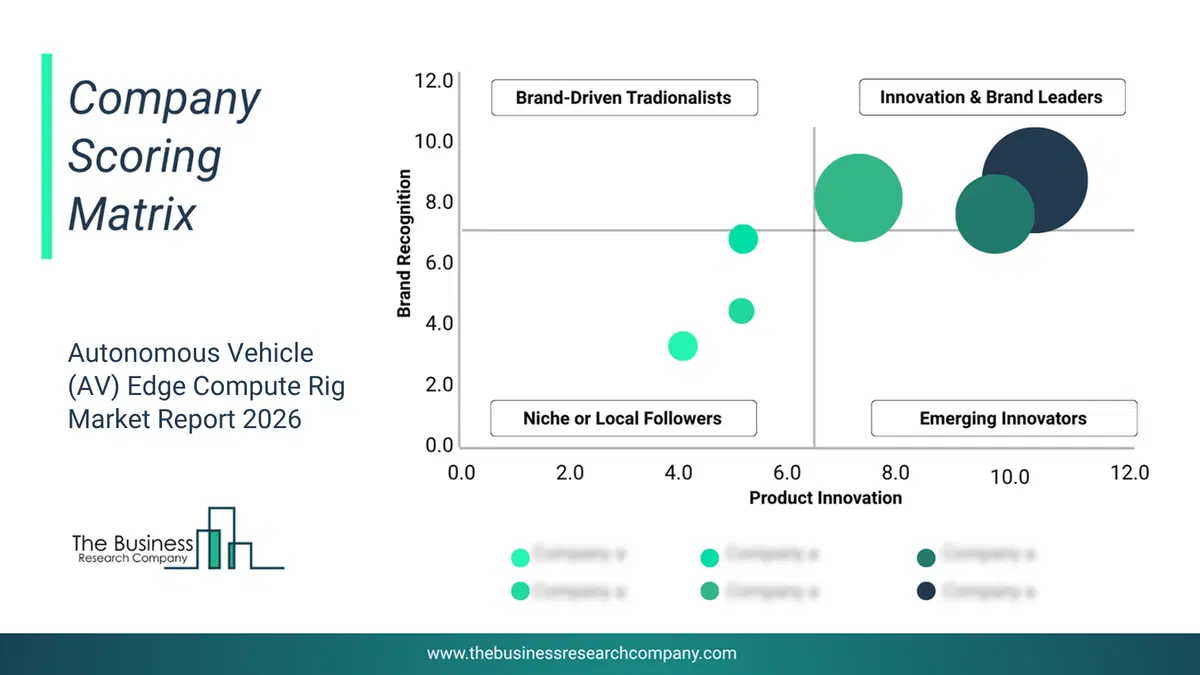
This chart maps companies by product innovation and brand strength, with bubble size indicating relative revenue, helping identify market leaders, challengers, and niche players. This is an illustrative chart; the full report provides a complete and accurate competitive analysis.
Regional Insights
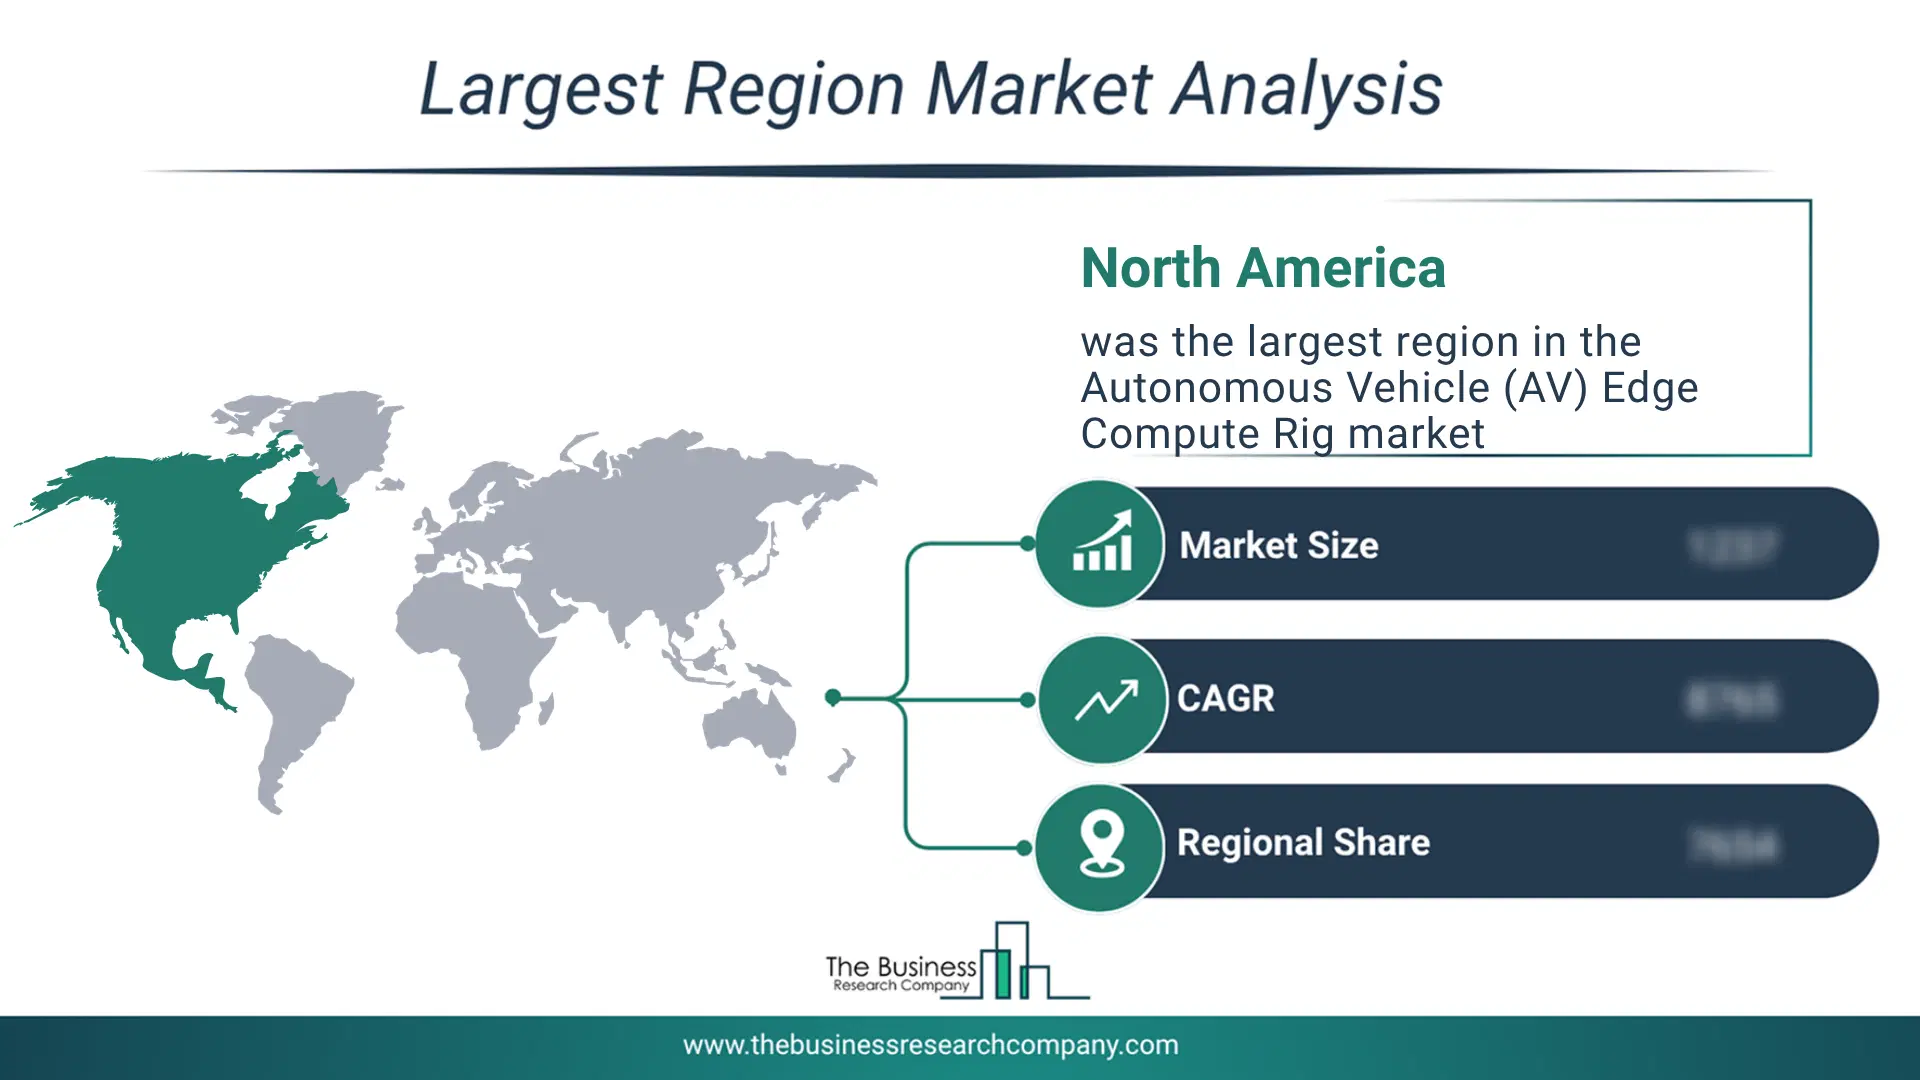
North America was the largest region in the autonomous vehicle (AV) edge compute rig market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in this market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa. The countries covered in this market report are Australia, Brazil, China, France, Germany, India, Indonesia, Japan, Taiwan, Russia, South Korea, UK, USA, Canada, Italy, Spain.What Defines the Autonomous Vehicle (AV) Edge Compute Rig Market?
The autonomous vehicle (AV) edge compute rig market consists of revenues earned by entities by providing services such as real-time data processing services, edge artificial intelligence (AI) model optimization, sensor data fusion services, predictive maintenance analytics, system integration services, and latency optimization services. The autonomous vehicle (AV) edge compute rig market also includes sales of high-speed sensors, lidar units, radar units, onboard networking switches, and vehicle-grade storage drives. Values in this market are ‘factory gate’ values, that is the value of goods sold by the manufacturers or creators of the goods, whether to other entities (including downstream manufacturers, wholesalers, distributors and retailers) or directly to end customers. The value of goods in this market includes related services sold by the creators of the goods.How is Market Value Defined and Measured?
The market value is defined as the revenues that enterprises gain from the sale of goods and/or services within the specified market and geography through sales, grants, or donations in terms of the currency (in USD unless otherwise specified). The revenues for a specified geography are consumption values that are revenues generated by organizations in the specified geography within the market, irrespective of where they are produced. It does not include revenues from resales along the supply chain, either further along the supply chain or as part of other products.
This chart presents market attractiveness based on a quantitative evaluation of growth, competition, strategic alignment, and risk, offering a clear view of opportunity areas for decision-making. This chart is for illustrative purposes; the full report contains the complete analysis.
This chart highlights the Total Addressable Market (TAM) by estimating the maximum revenue opportunity using an assumption-driven approach, supporting strategic planning and opportunity sizing across markets. The chart is illustrative; the full report provides a more comprehensive analysis.
What Key Data and Analysis Are Included in the Autonomous Vehicle (AV) Edge Compute Rig Market Report 2026?
The autonomous vehicle (av) edge compute rig market research report is one of a series of new reports from The Business Research Company that provides market statistics, including industry global market size, regional shares, competitors with the market share, detailed market segments, market trends and opportunities, and any further data you may need to thrive in the autonomous vehicle (av) edge compute rig industry. The market research report delivers a complete perspective of everything you need, with an in-depth analysis of the current and future state of the industry.Autonomous Vehicle (AV) Edge Compute Rig Market Report Forecast Analysis
| Report Attribute | Details |
|---|---|
| Market Size Value In 2026 | $4.10 billion |
| Revenue Forecast In 2030 | $9.14 billion |
| Growth Rate | CAGR of 22.2% from 2026 to 2030 |
| Base Year For Estimation | 2025 |
| Actual Estimates/Historical Data | 2020-2025 |
| Forecast Period | 2026 - 2030 |
| Market Representation | Revenue in USD Billion and CAGR from 2026 to 2030 |
| Segments Covered | Component, Deployment or Delivery Model, Application Type, End-User or Client Size |
| Regional Scope | Asia-Pacific, Western Europe, Eastern Europe, North America, South America, Middle East, Africa |
| Country Scope | The Countries Covered In This Market Report Are Australia, Brazil, China, France, Germany, India, Indonesia, Japan, Taiwan, Russia, South Korea, Uk, Usa, Canada, Italy, Spain. |
| Key Companies Profiled | Tesla Inc., Robert Bosch GmbH, NVIDIA Corporation, Continental AG, Qualcomm Incorporated, Advanced Micro Devices Inc. (AMD), Aptiv PLC, Texas Instruments Incorporated, Infineon Technologies AG, STMicroelectronics N.V., NXP Semiconductors N.V., Renesas Electronics Corporation, Microchip Technology Inc., ON Semiconductor Corporation, Lattice Semiconductor Corporation, ADLINK Technology Inc., Lanner Electronics Inc., AAEON Technology Inc., Horizon Robotics Inc., Vecow Co. Ltd. |
| Customization Scope | Request for Customization |
| Pricing And Purchase Options | Explore Purchase Options |