Military Aircraft And Aerospace Manufacturing Market Report 2026
Global Outlook – By Product (Aircraft Parts, Avionics And Electronic Systems, Maintenance, Repair And Overhaul And Other Services, Missiles And Space Systems), By Aircraft Type (Fixed Wing Aircraft, Rotary Wing Aircraft, Unmanned Aircraft), By Propulsion (Turbofan Engine, Turboprop Engine, Turboshaft Engine, Piston Engine), By Sales Channel (Direct Government Contracts, Defense System Integrators), By End User (Air Force, Army Aviation, Naval Aviation) – Market Size, Trends, Strategies, and Forecast to 2030
Military Aircraft And Aerospace Manufacturing Market Overview
• Military Aircraft And Aerospace Manufacturing market size has reached to $311.84 billion in 2025 • Expected to grow to $492.51 billion in 2030 at a compound annual growth rate (CAGR) of 9.6% • Growth Driver: Increasing Defense Modernization Programs Drive The Market Growth Due To Rising Geopolitical Tensions • Market Trend: Innovations In Uncrewed Collaborative Combat Aircraft Strengthen Military Aircraft And Aerospace Manufacturing Capabilities • North America was the largest region in 2025 and Asia-Pacific is the fastest growing region.What Is Covered Under Military Aircraft And Aerospace Manufacturing Market?
Military aircraft and aerospace manufacturing is the industrial sector involved in the design, engineering, production, assembly, and testing of advanced aerospace systems and defense aviation technologies. It supports national defense capabilities by delivering highly specialized aerospace platforms built to meet stringent performance, safety, and regulatory standards. The main products of military aircraft and aerospace manufacturing include aircraft parts, avionics and electronic systems, maintenance, repair and overhaul and other services, and missiles and space systems. Aircraft parts refer to structural, mechanical, and other components manufactured for military aircraft and aerospace platforms to support their assembly, operation, and maintenance. These products are used across fixed wing aircraft, rotary wing aircraft, and unmanned aircraft, and are powered by turbofan engines, turboprop engines, turboshaft engines, and piston engines. They are sold through direct government contracts and defense system integrators, and are used by end users including air force, army aviation, and naval aviation.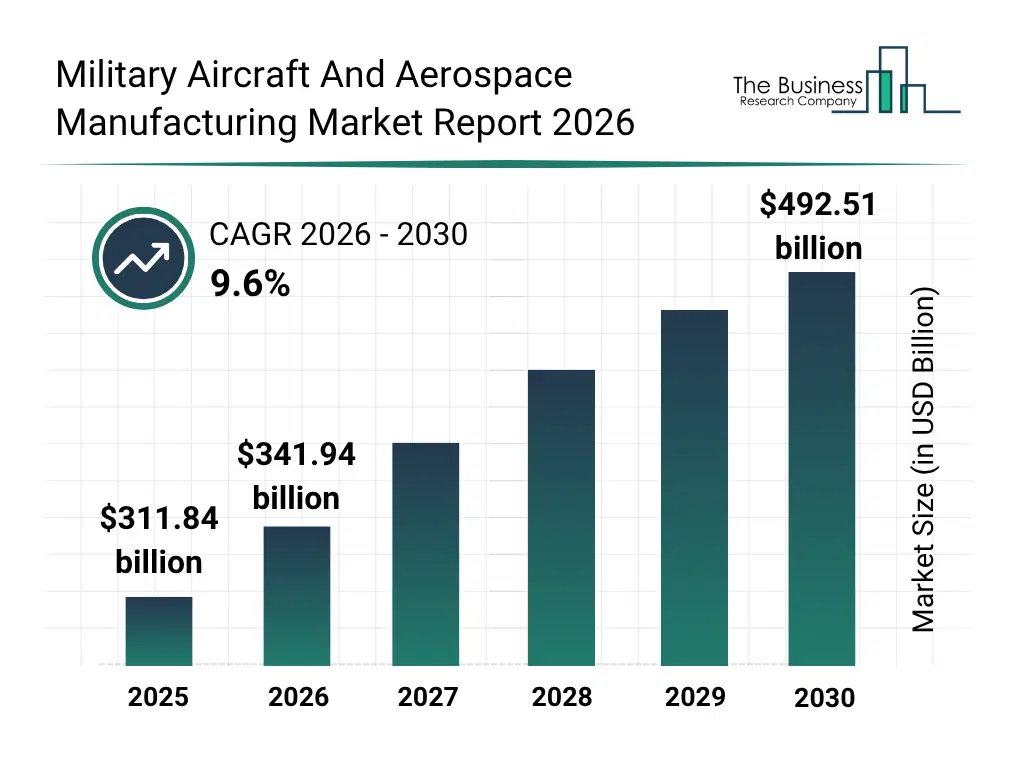
What Is The Military Aircraft And Aerospace Manufacturing Market Size and Share 2026?
The military aircraft and aerospace manufacturing market size has grown strongly in recent years. It will grow from $311.84 billion in 2025 to $341.94 billion in 2026 at a compound annual growth rate (CAGR) of 9.7%. The growth in the historic period can be attributed to rising defense spending, increasing military aircraft procurement, replacement of aging aircraft fleets, expansion of national aerospace capabilities, growing geopolitical tensions.What Is The Military Aircraft And Aerospace Manufacturing Market Growth Forecast?
The military aircraft and aerospace manufacturing market size is expected to see strong growth in the next few years. It will grow to $492.51 billion in 2030 at a compound annual growth rate (CAGR) of 9.6%. The growth in the forecast period can be attributed to increasing defense modernization programs, rising demand for next-generation fighter aircraft, growing procurement of unmanned aircraft, increasing investments in advanced military avionics, expansion of domestic aerospace manufacturing capabilities. Major trends in the forecast period include increasing adoption of advanced military aircraft, development of next-generation fighter aircraft, growing demand for unmanned military aircraft, expansion of military aircraft modernization programs, increasing integration of advanced avionics and electronic warfare systems.
Global Military Aircraft And Aerospace Manufacturing Market Segmentation
1) By Product: Aircraft Parts, Avionics And Electronic Systems, Maintenance, Repair And Overhaul And Other Services, Missiles And Space Systems 2) By Aircraft Type: Fixed Wing Aircraft, Rotary Wing Aircraft, Unmanned Aircraft 3) By Propulsion: Turbofan Engine, Turboprop Engine, Turboshaft Engine, Piston Engine 4) By Sales Channel: Direct Government Contracts, Defense System Integrators 5) By End User: Air Force, Army Aviation, Naval Aviation Subsegments: 1) By Aircraft Parts: Airframes, Aircraft Engines, Landing Gear Systems, Flight Control Surfaces, Fuel Systems 2) By Avionics And Electronic Systems: Flight Management Systems, Communication Systems, Navigation Systems, Radar And Surveillance Systems, Electronic Warfare Systems 3) By Maintenance, Repair And Overhaul And Other Services: Airframe Maintenance, Engine Maintenance, Component Repair And Overhaul, Avionics Maintenance, Technical Support And Engineering Services 4) By Missiles And Space Systems: Air To Air Missiles, Air To Ground Missiles, Launch Vehicles, Military Satellites, Spacecraft SystemsWhat Is The Driver Of The Military Aircraft And Aerospace Manufacturing Market?
The increasing defense modernization programs are expected to propel the growth of the military aircraft and aerospace manufacturing market going forward. Defense modernization programs are government initiatives that upgrade military capabilities through investments in advanced technologies, modern equipment, and enhanced defense infrastructure to improve national security and operational readiness. Defense modernization programs are increasing due to rising geopolitical tensions, as governments invest in advanced defense technologies and modern equipment to address evolving regional conflicts and security threats. Defense modernization programs drive the military aircraft and aerospace manufacturing by increasing government investments in the development, production, and procurement of advanced military aircraft, aerospace systems, and related technologies. For instance, in March 2023, according to the Offices of the Under Secretaries of Defense (OUSD), a US-based Department of Defense authority, the fiscal year 2024 Cybersecurity and Acquisition budget of $13.5 billion, aligned with the 2022 National Defense Strategy, is designed to strengthen ongoing efforts under the Digital Modernization Strategy and the Department of Defense Cyber Strategy framework. Therefore, the increasing defense modernization programs are driving the growth of the military aircraft and aerospace manufacturing industry.Key Players In The Global Military Aircraft And Aerospace Manufacturing Market
Major companies operating in the military aircraft and aerospace manufacturing market are Aviation Industry Corporation of China, The Boeing Company, Airbus SE, RTX Corporation, Lockheed Martin Corporation, General Dynamics Corporation, Northrop Grumman Corporation, GE Aerospace, Honeywell Aerospace Technologies, BAE Systems plc, Mitsubishi Heavy Industries Ltd, Safran SA, Thales SA, Rolls-Royce Holdings plc, L3Harris Technologies Inc, Leonardo SpA, Textron Inc, Rheinmetall AG, Elbit Systems Ltd, Dassault Aviation SA, Embraer SA, Saab AB, Israel Aerospace Industries Ltd, Kongsberg Gruppen ASA, Hindustan Aeronautics Limited, Moog Inc, Turkish Aerospace Industries Inc, Korea Aerospace Industries Ltd, Curtiss-Wright Corporation
This chart is for illustrative purposes; the full report includes a detailed competitor analysis and comprehensive overview of the top 10 companies in the market.
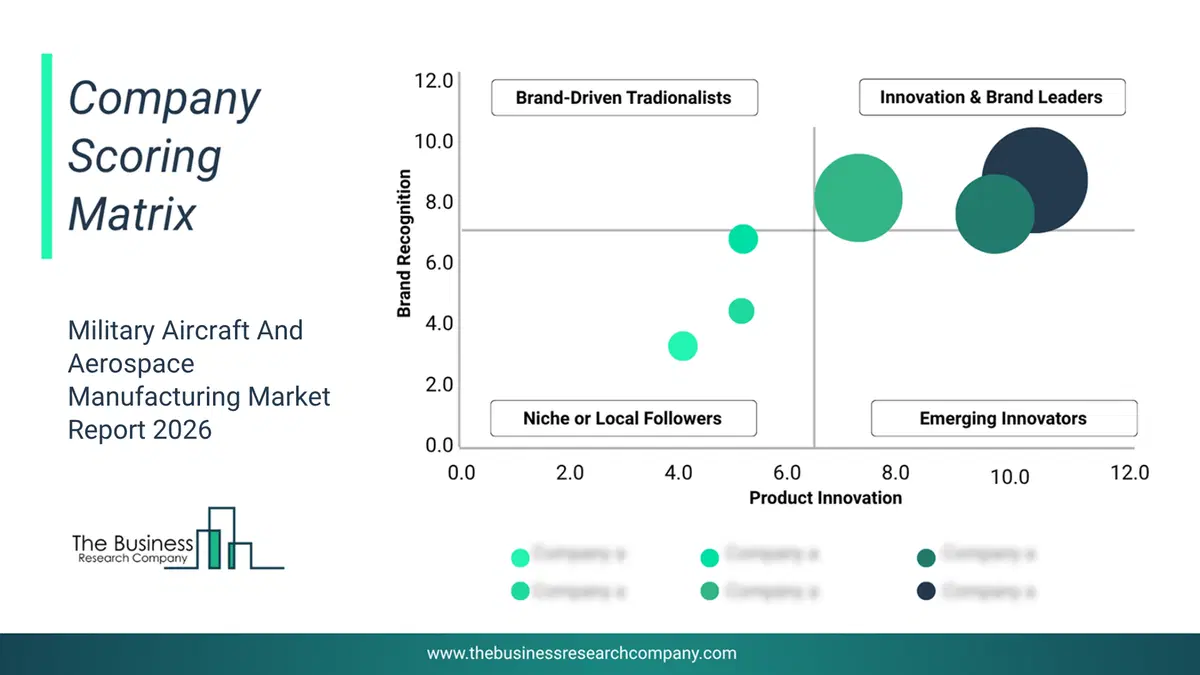
This chart maps companies by product innovation and brand strength, with bubble size indicating relative revenue, helping identify market leaders, challengers, and niche players. This is an illustrative chart; the full report provides a complete and accurate competitive analysis.
Global Military Aircraft And Aerospace Manufacturing Market Trends and Insights
Major companies operating in the military aircraft and aerospace manufacturing market are focusing on developing advanced solutions, such as uncrewed collaborative combat aircraft, to enhance combat effectiveness, improve mission survivability, and support crewed aircraft in high-risk operations. Uncrewed collaborative combat aircraft are autonomous or remotely controlled military aircraft designed to operate alongside crewed fighter jets, performing missions such as reconnaissance, electronic warfare, and precision strikes. For instance, in June 2024, Airbus SE, a Netherlands-based aerospace company, unveiled its Wingman concept, an uncrewed collaborative combat aircraft designed to operate alongside Eurofighter combat aircraft. The concept incorporates low-observable design, advanced sensors, secure connectivity, and integrated weapon systems to support crewed fighter aircraft in complex missions. It enables pilots to assign high-risk operations to the uncrewed aircraft while maintaining mission control, improving operational flexibility and overall combat capability.What Are Latest Mergers And Acquisitions In The Military Aircraft And Aerospace Manufacturing Market?
In June 2025, Dassault Aviation, a France-based military aircraft manufacturer, partnered with Tata Advanced Systems Limited (TASL) to establish India as a global manufacturing hub for Rafale fighter aircraft fuselages while strengthening the international aerospace supply chain. Through this partnership, the companies aim to manufacture Rafale fighter aircraft fuselages in India for domestic and global markets, strengthen aerospace manufacturing capabilities, expand the global supply chain, and support increased production of Rafale fighter aircraft. Tata Advanced Systems Limited is an India-based aerospace and defense company that designs, develops, and manufactures military aircraft structures, aerospace systems, unmanned platforms, and defense equipment.
Regional Outlook
North America was the largest region in the military aircraft and aerospace manufacturing market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in this market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa. The countries covered in this market report are Australia, Brazil, China, France, Germany, India, Indonesia, Japan, Taiwan, Russia, South Korea, UK, USA, Canada, Italy, Spain.What Defines the Military Aircraft And Aerospace Manufacturing Market?
The military aircraft and aerospace manufacturing market consists of revenues earned by entities by providing services such as aircraft design and engineering, military aircraft manufacturing, aerospace systems integration, and prototype development and testing. The market value includes the value of related goods sold by the service provider or included within the service offering. The military aircraft and aerospace manufacturing market also includes sales of military aircraft, fighter aircraft, military transport aircraft, and military helicopters. Values in this market are ‘factory gate’ values, that is, the value of goods sold by the manufacturers or creators of the goods, whether to other entities (including downstream manufacturers, wholesalers, distributors, and retailers) or directly to end customers. The value of goods in this market includes related services sold by the creators of the goods.How is Market Value Defined and Measured?
The market value is defined as the revenues that enterprises gain from the sale of goods and/or services within the specified market and geography through sales, grants, or donations in terms of the currency (in USD unless otherwise specified). The revenues for a specified geography are consumption values that are revenues generated by organizations in the specified geography within the market, irrespective of where they are produced. It does not include revenues from resales along the supply chain, either further along the supply chain or as part of other products.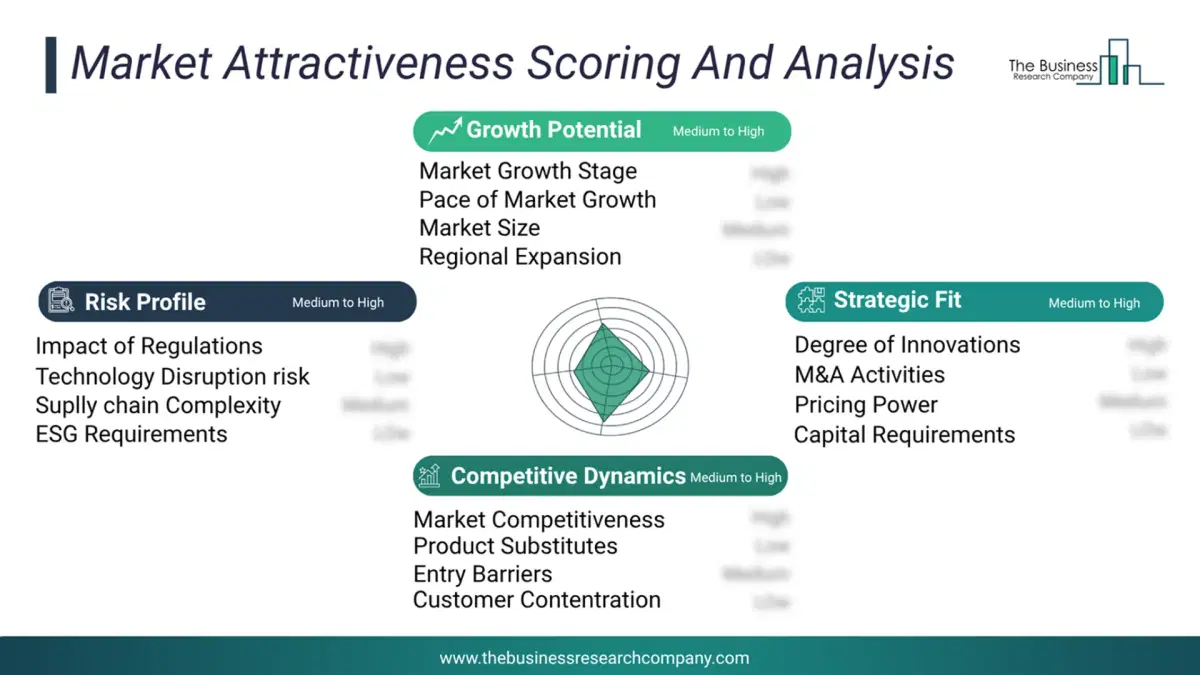
This chart presents market attractiveness based on a quantitative evaluation of growth, competition, strategic alignment, and risk, offering a clear view of opportunity areas for decision-making. This chart is for illustrative purposes; the full report contains the complete analysis.
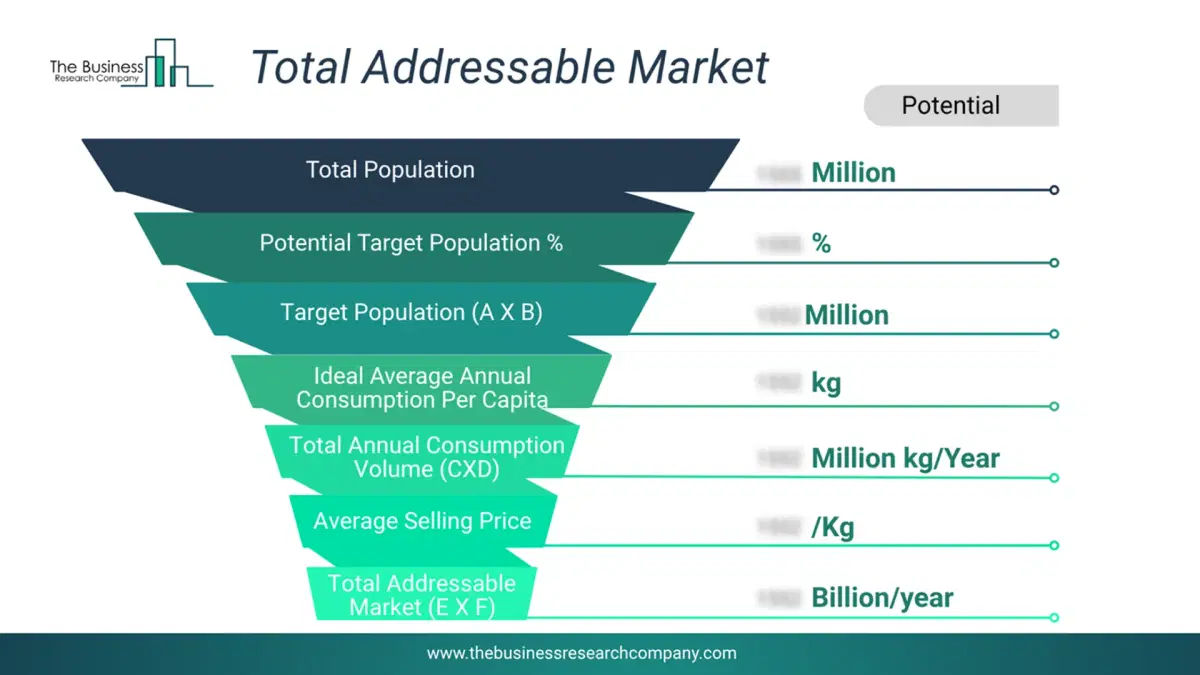
This chart highlights the Total Addressable Market (TAM) by estimating the maximum revenue opportunity using an assumption-driven approach, supporting strategic planning and opportunity sizing across markets. The chart is illustrative; the full report provides a more comprehensive analysis.
What Key Data and Analysis Are Included in the Military Aircraft And Aerospace Manufacturing Market Report 2026?
The military aircraft and aerospace manufacturing market research report is one of a series of new reports from The Business Research Company that provides market statistics, including industry global market size, regional shares, competitors with the market share, detailed market segments, market trends and opportunities, and any further data you may need to thrive in the military aircraft and aerospace manufacturing industry. The market research report delivers a complete perspective of everything you need, with an in-depth analysis of the current and future state of the industry.Military Aircraft And Aerospace Manufacturing Market Report Forecast Analysis
| Report Attribute | Details |
|---|---|
| Market Size Value In 2026 | $341.94 billion |
| Revenue Forecast In 2030 | $492.51 billion |
| Growth Rate | CAGR of 9.6% from 2026 to 2030 |
| Base Year For Estimation | 2025 |
| Actual Estimates/Historical Data | 2020-2025 |
| Forecast Period | 2026 - 2030 |
| Market Representation | Revenue in USD Billion and CAGR from 2026 to 2030 |
| Segments Covered | Product, Aircraft Type, Propulsion, Sales Channel, End User |
| Regional Scope | Asia-Pacific, Western Europe, Eastern Europe, North America, South America, Middle East, Africa |
| Country Scope | The countries covered in the report are Australia, Brazil, China, France, Germany, India, Indonesia, Japan, Taiwan, Russia, South Korea, UK, USA, Canada, Italy, Spain. |
| Key Companies Profiled | Aviation Industry Corporation of China, The Boeing Company, Airbus SE, RTX Corporation, Lockheed Martin Corporation, General Dynamics Corporation, Northrop Grumman Corporation, GE Aerospace, Honeywell Aerospace Technologies, BAE Systems plc, Mitsubishi Heavy Industries Ltd, Safran SA, Thales SA, Rolls-Royce Holdings plc, L3Harris Technologies Inc, Leonardo SpA, Textron Inc, Rheinmetall AG, Elbit Systems Ltd, Dassault Aviation SA, Embraer SA, Saab AB, Israel Aerospace Industries Ltd, Kongsberg Gruppen ASA, Hindustan Aeronautics Limited, Moog Inc, Turkish Aerospace Industries Inc, Korea Aerospace Industries Ltd, Curtiss-Wright Corporation |
| Customization Scope | Request for Customization |
| Pricing And Purchase Options | Explore Purchase Options |