
Thin Film Semiconductor Deposition Market Report 2026
Global Outlook – By Technology (Chemical Vapor Deposition, Physical Vapor Deposition, Atomic Layer Deposition, Electrochemical Deposition, Molecular Beam Epitaxy), By Deposition Material (Metal Thin Films, Dielectric Thin Films, Semiconductor Thin Films, Organic Thin Films, Compound Semiconductor Thin Films), By Application (Integrated Circuits, Memory Devices, Logic Devices, Micro-Electro-Mechanical Systems, Optoelectronic Devices), By End User (Consumer Electronics, Automotive, Energy And Power, Aerospace And Defense, Communication And Technology, Other End Users) – Market Size, Trends, Strategies, and Forecast to 2030
Thin Film Semiconductor Deposition Market Overview
• Thin Film Semiconductor Deposition market size has reached to $18.63 billion in 2025 • Expected to grow to $32.78 billion in 2030 at a compound annual growth rate (CAGR) of 11.9% • Growth Driver: Rising Demand For Consumer Electronics Driving Growth Of The Market Due To Increasing Adoption Of Smart And Connected Devices • Market Trend: Innovation In Bio-Based Unsaturated Polyester Resins Driving Sustainable Thermosetting Resin Development • Asia-Pacific was the largest region and fastest growing region.What Is Covered Under Thin Film Semiconductor Deposition Market?
Thin film semiconductor deposition is the process of forming ultra-thin layers of semiconductor materials on a substrate with precise control over thickness, composition, and uniformity to create functional electronic materials. It encompasses a range of deposition technologies used to produce high-quality semiconductor films that support the fabrication of advanced microelectronic and optoelectronic devices. The main technologies of thin film semiconductor deposition include chemical vapor deposition, physical vapor deposition, atomic layer deposition, electrochemical deposition, and molecular beam epitaxy. Chemical vapor deposition refers to a process in which gaseous precursors react or decompose on a substrate surface to form a thin semiconductor film with controlled thickness and composition. These technologies deposit metal thin films, dielectric thin films, semiconductor thin films, organic thin films, and compound semiconductor thin films. The key applications include integrated circuits, memory devices, logic devices, micro-electro-mechanical systems, and optoelectronic devices, while the end-users include consumer electronics, automotive, energy and power, aerospace and defense, communication and technology, and others.
What Is The Thin Film Semiconductor Deposition Market Size and Share 2026?
The thin film semiconductor deposition market size has grown rapidly in recent years. It will grow from $18.63 billion in 2025 to $20.92 billion in 2026 at a compound annual growth rate (CAGR) of 12.3%. The growth in the historic period can be attributed to rising semiconductor manufacturing activity, increasing demand for advanced microelectronic devices, growing adoption of thin film deposition in integrated circuit fabrication, increasing production of optoelectronic components, expanding semiconductor fabrication capacity.What Is The Thin Film Semiconductor Deposition Market Growth Forecast?
The thin film semiconductor deposition market size is expected to see rapid growth in the next few years. It will grow to $32.78 billion in 2030 at a compound annual growth rate (CAGR) of 11.9%. The growth in the forecast period can be attributed to growing demand for advanced node semiconductor devices, rising adoption of compound semiconductor technologies, increasing demand for high-uniformity deposition processes, expanding fabrication of advanced memory and logic devices, growing investment in semiconductor manufacturing infrastructure. Major trends in the forecast period include increasing adoption of atomic layer deposition for advanced semiconductor films, growing demand for ultra-thin and highly uniform semiconductor layers, rising development of low-temperature deposition processes, increasing use of compound semiconductor deposition materials, growing demand for high-precision deposition equipment.

Global Thin Film Semiconductor Deposition Market Segmentation
1) By Technology: Chemical Vapor Deposition, Physical Vapor Deposition, Atomic Layer Deposition, Electrochemical Deposition, Molecular Beam Epitaxy 2) By Deposition Material: Metal Thin Films, Dielectric Thin Films, Semiconductor Thin Films, Organic Thin Films, Compound Semiconductor Thin Films 3) By Application: Integrated Circuits, Memory Devices, Logic Devices, Micro-Electro-Mechanical Systems, Optoelectronic Devices 4) By End User: Consumer Electronics, Automotive, Energy And Power, Aerospace And Defense, Communication And Technology, Other End Users Subsegments: 1) By Chemical Vapor Deposition: Atmospheric Pressure Chemical Vapor Deposition, Low Pressure Chemical Vapor Deposition, Plasma Enhanced Chemical Vapor Deposition, Metal Organic Chemical Vapor Deposition, Photo Assisted Chemical Vapor Deposition 2) By Physical Vapor Deposition: Thermal Evaporation, Electron Beam Evaporation, Magnetron Sputtering, Ion Beam Deposition, Pulsed Laser Deposition 3) By Atomic Layer Deposition: Thermal Atomic Layer Deposition, Plasma Enhanced Atomic Layer Deposition, Spatial Atomic Layer Deposition, Catalytic Atomic Layer Deposition, Radical Enhanced Atomic Layer Deposition 4) By Electrochemical Deposition: Electroplating, Electroless Deposition, Pulse Electroplating, Brush Electroplating 5) By Molecular Beam Epitaxy: Solid Source Molecular Beam Epitaxy, Gas Source Molecular Beam Epitaxy, Chemical Beam Epitaxy, Plasma Assisted Molecular Beam EpitaxyWhat Is The Driver Of The Thin Film Semiconductor Deposition Market?
The rising demand for consumer electronics is expected to propel the growth of the thin film semiconductor deposition market going forward. Consumer electronics are electronic products manufactured for everyday personal use, enabling users to access digital communication, entertainment, information, and smart connectivity. Consumer electronics demand is increasing due to the growing adoption of smart and connected technologies that provide enhanced convenience, seamless connectivity, and improved user experiences. The growing demand for consumer electronics is driving the need for advanced semiconductor chips, increasing the adoption of thin film semiconductor deposition to enable high-performance, miniaturized, and energy-efficient devices. For instance, in May 2023, according to the Japan Electronics and Information Technology Industries Association, a Japan-based trade association, the total consumer electronic equipment production in Japan reached $209.16 million (¥32,099 million), compared to $164.65 million (¥25,268 million) in May 2022. Therefore, the rising demand for consumer electronics is driving the growth of the thin-film semiconductor deposition market.Key Players In The Global Thin Film Semiconductor Deposition Market
Major companies operating in the thin film semiconductor deposition market are Applied Materials Inc, Tokyo Electron Limited, Lam Research Corporation, ASM International NV, Kokusai Electric Corporation, NAURA Technology Group, Advanced Micro Fabrication Equipment Inc, Veeco Instruments Inc, AIXTRON SE, Oxford Instruments plc, ULVAC Inc, Wonik IPS Co Ltd, Evatec AG, Jusung Engineering Co Ltd, SUSS MicroTec SE, Shibaura Mechatronics Corporation, Canon ANELVA Corporation, Singulus Technologies AG, Kurt J Lesker Company, Beneq Oy, SENTECH Instruments GmbH, CVD Equipment Corporation, Angstrom Engineering Inc, AJA International Inc, Mattson Technology Inc, Onto Innovation Inc, Hitachi High Tech Corporation, TES Co Ltd
This chart is for illustrative purposes; the full report includes a detailed competitor analysis and comprehensive overview of the top 10 companies in the market.

This chart maps companies by product innovation and brand strength, with bubble size indicating relative revenue, helping identify market leaders, challengers, and niche players. This is an illustrative chart; the full report provides a complete and accurate competitive analysis.
Global Thin Film Semiconductor Deposition Market Trends and Insights
Major companies operating in the thin-film semiconductor deposition market are focusing on developing innovative solutions such as single-wafer deposition systems to improve deposition precision, increase manufacturing productivity, and support advanced semiconductor device fabrication. Single-wafer deposition systems refer to semiconductor manufacturing equipment that deposits thin films on individual wafers with precise process control, enabling high uniformity, improved yield, and enhanced performance for advanced chip production. For instance, in July 2024, Tokyo Electron Limited, a Japan-based semiconductor equipment manufacturer, launched the Episode 1 and Episode 2 DMR single-wafer deposition systems and announced the planned release of the Episode 2 QMR. The products are designed to perform highly precise thin-film deposition for advanced semiconductor manufacturing. They offer benefits such as improved film uniformity, enhanced process flexibility, and higher production throughput. The launch aims to help customers manufacture next-generation semiconductor devices with greater efficiency while supporting ongoing advancements in semiconductor process technology.What Are Latest Mergers And Acquisitions In The Thin Film Semiconductor Deposition Market?
In February 2023, Veeco Instruments Inc., a US-based semiconductor equipment manufacturer, acquired Epiluvac AB for an undisclosed amount. Through this acquisition, Veeco aims to accelerate its penetration into the high-growth silicon carbide (SIC) epitaxy equipment market by combining Epiluvac's advanced CVD epitaxy technology with its global manufacturing, sales, and service capabilities. Epiluvac AB is a Sweden-based manufacturer in thin film semiconductor deposition, specifically in the chemical vapor deposition (CVD) epitaxy equipment segment.
Regional Outlook
Asia-Pacific was the largest region in the thin film semiconductor deposition market in 2025. Asia-Pacific is expected to be the fastest-growing region in the forecast period. The regions covered in this market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa. The countries covered in this market report are Australia, Brazil, China, France, Germany, India, Indonesia, Japan, Taiwan, Russia, South Korea, UK, USA, Canada, Italy, Spain.What Defines the Thin Film Semiconductor Deposition Market?
The thin-film semiconductor deposition market consists of revenues earned by entities by providing services such as wafer coating, dielectric layer deposition, barrier film deposition, and surface passivation. The market value includes the value of related goods sold by the service provider or included within the service offering. The thin-film semiconductor deposition market also includes sales of thin-film transistors (TFTs), power semiconductor devices, radio frequency (RF) semiconductor devices, and semiconductor sensors. Values in this market are ‘factory gate’ values, that is, the value of goods sold by the manufacturers or creators of the goods, whether to other entities (including downstream manufacturers, wholesalers, distributors, and retailers) or directly to end customers. The value of goods in this market includes related services sold by their creators.How is Market Value Defined and Measured?
The market value is defined as the revenues that enterprises gain from the sale of goods and/or services within the specified market and geography through sales, grants, or donations in terms of the currency (in USD unless otherwise specified). The revenues for a specified geography are consumption values that are revenues generated by organizations in the specified geography within the market, irrespective of where they are produced. It does not include revenues from resales along the supply chain, either further along the supply chain or as part of other products.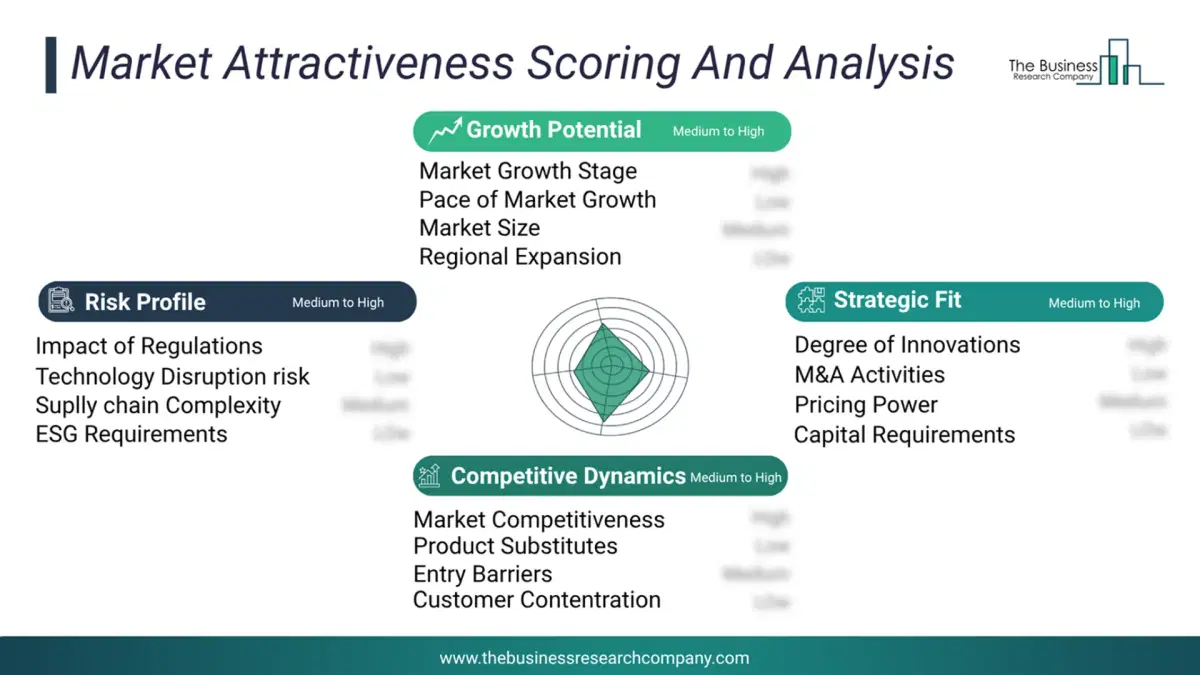
This chart presents market attractiveness based on a quantitative evaluation of growth, competition, strategic alignment, and risk, offering a clear view of opportunity areas for decision-making. This chart is for illustrative purposes; the full report contains the complete analysis.
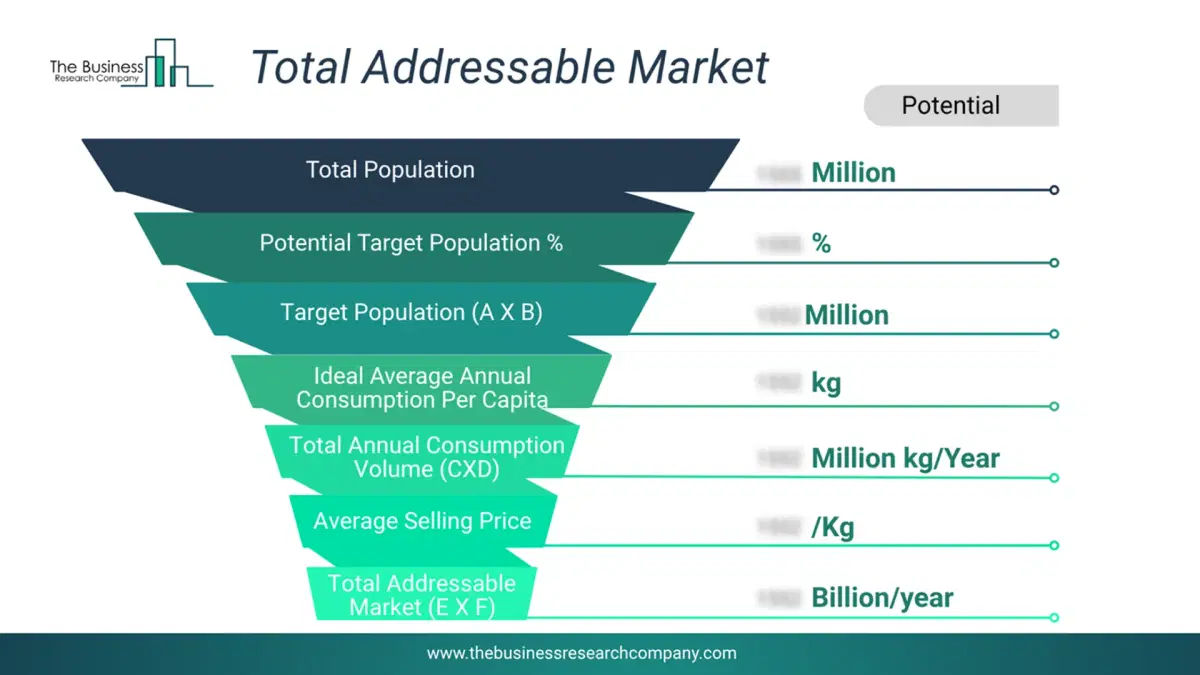
This chart highlights the Total Addressable Market (TAM) by estimating the maximum revenue opportunity using an assumption-driven approach, supporting strategic planning and opportunity sizing across markets. The chart is illustrative; the full report provides a more comprehensive analysis.
What Key Data and Analysis Are Included in the Thin Film Semiconductor Deposition Market Report 2026?
The thin film semiconductor deposition market research report is one of a series of new reports from The Business Research Company that provides market statistics, including industry global market size, regional shares, competitors with the market share, detailed market segments, market trends and opportunities, and any further data you may need to thrive in the thin film semiconductor deposition industry. The market research report delivers a complete perspective of everything you need, with an in-depth analysis of the current and future state of the industry.Thin Film Semiconductor Deposition Market Report Forecast Analysis
| Report Attribute | Details |
|---|---|
| Market Size Value In 2026 | $20.92 billion |
| Revenue Forecast In 2030 | $32.78 billion |
| Growth Rate | CAGR of 11.9% from 2026 to 2030 |
| Base Year For Estimation | 2025 |
| Actual Estimates/Historical Data | 2020-2025 |
| Forecast Period | 2026 - 2030 |
| Market Representation | Revenue in USD Billion and CAGR from 2026 to 2030 |
| Segments Covered | Technology, Deposition Material, Application, End User |
| Regional Scope | Asia-Pacific, Western Europe, Eastern Europe, North America, South America, Middle East, Africa |
| Country Scope | The countries covered in the report are Australia, Brazil, China, France, Germany, India, Indonesia, Japan, Taiwan, Russia, South Korea, UK, USA, Canada, Italy, Spain. |
| Key Companies Profiled | Applied Materials Inc, Tokyo Electron Limited, Lam Research Corporation, ASM International NV, Kokusai Electric Corporation, NAURA Technology Group, Advanced Micro Fabrication Equipment Inc, Veeco Instruments Inc, AIXTRON SE, Oxford Instruments plc, ULVAC Inc, Wonik IPS Co Ltd, Evatec AG, Jusung Engineering Co Ltd, SUSS MicroTec SE, Shibaura Mechatronics Corporation, Canon ANELVA Corporation, Singulus Technologies AG, Kurt J Lesker Company, Beneq Oy, SENTECH Instruments GmbH, CVD Equipment Corporation, Angstrom Engineering Inc, AJA International Inc, Mattson Technology Inc, Onto Innovation Inc, Hitachi High Tech Corporation, TES Co Ltd |
| Customization Scope | Request for Customization |
| Pricing And Purchase Options | Explore Purchase Options |