
N-type Semiconductor Material Market Report 2026
Global Outlook – By Material Type ( Silicon, Germanium, Gallium Arsenide, Silicon Carbide, Other Material Types), By Device Type ( Integrated Circuits (ICs), Microcontrollers, Power Devices, Optoelectronics, Radio-Frequency (RF) Devices), By Doping Material ( Phosphorus-Doped, Arsenic-Doped, Other Doping Materials), By Application ( Consumer Electronics, Automotive, Industrial, Telecommunication, Other Applications) – Market Size, Trends, Strategies, and Forecast to 2030
N-type Semiconductor Material Market Overview
• N-type Semiconductor Material market size has reached to $34.83 billion in 2025 • Expected to grow to $47.91 billion in 2030 at a compound annual growth rate (CAGR) of 6.5% • Growth Driver: Increased Production Of Photovoltaic Cells Fueled The Market Due To Increasing Solar Energy Deployment • Market Trend: Technological Advancement In High-Efficiency N-Type Module Manufacturing With Narrowed Cell Spacing • Asia-Pacific was the largest region in 2025 and North America is the fastest growing region.Market Gains By 2030 – Top Opportunities By Segment
Market Gain identifies the most promising market opportunities by highlighting the segments or products expected to generate the highest incremental revenue growth over the next five years.
What Is Covered Under N-type Semiconductor Material Market?
N-type semiconductor material is a type of semiconductor that has been doped with pentavalent elements, such as phosphorus, arsenic, or antimony, which add extra electrons as charge carriers. These free electrons enable efficient electrical conduction. It helps to provide electron-rich pathways for current flow, making them essential in devices such as diodes, transistors, integrated circuits, power electronics, and high-frequency applications, and are often paired with P-type semiconductors to form functional electronic components. The main material types of N-type semiconductor material are silicon, germanium, gallium arsenide, silicon carbide, and others. Silicon refers to the base semiconductor that is doped with pentavalent atoms (such as phosphorus or arsenic) to add extra electrons as charge carriers, making electrons the majority carriers. It includes various device types such as integrated circuits (ICs), microcontrollers, power devices, optoelectronics, and radio-frequency (RF) devices, and uses different doping materials, including phosphorus-doped, arsenic-doped, and others. It is used in applications such as consumer electronics, automotive, industrial, telecommunication, and others.
What Is The N-type Semiconductor Material Market Size 2026 And Growth Rate?
The n-type semiconductor material market size has grown strongly in recent years. It will grow from $34.83 billion in 2025 to $37.21 billion in 2026 at a compound annual growth rate (CAGR) of 6.8%. The growth in the historic period can be attributed to increasing need for faster electronic switching, early adoption of semiconductor-based consumer devices, growth in telecom infrastructure, rising production of integrated circuits, advancements in doping and fabrication methods.What Is The N-type Semiconductor Material Market Growth Forecast?
The n-type semiconductor material market size is expected to see strong growth in the next few years. It will grow to $47.91 billion in 2030 at a compound annual growth rate (CAGR) of 6.5%. The growth in the forecast period can be attributed to expansion of ev and power electronics demand, rising miniaturization of electronic components, increasing use of wide-bandgap semiconductors like sic and gan, growth in AI and iot-enabled devices, expansion of rf and high-frequency device applications. Major trends in the forecast period include rising adoption of high-frequency semiconductor devices, advancements in doping techniques for enhanced electron mobility, growing demand for power-efficient electronic components, increasing integration of n-type materials in miniaturized circuits, rising use of wide-bandgap semiconductor materials.

Global N-type Semiconductor Material Market Segmentation
1) By Material Type: Silicon, Germanium, Gallium Arsenide, Silicon Carbide, Other Material Types 2) By Device Type: Integrated Circuits (ICs), Microcontrollers, Power Devices, Optoelectronics, Radio-Frequency (RF) Devices 3) By Doping Material: Phosphorus-Doped, Arsenic-Doped, Other Doping Materials 4) By Application: Consumer Electronics, Automotive, Industrial, Telecommunication, Other Applications Subsegments: 1) By Silicon: Monocrystalline, Polycrystalline, Amorphous 2) By Germanium: Single Crystal, Polycrystalline, Epitaxial Layer 3) By Gallium Arsenide: Bulk Crystal, Epitaxial Wafer, Thin Film 4) By Silicon Carbide: Hexagonal, Cubic, Polytype 5) By Other Material Types: Indium Phosphide, Gallium Nitride, Zinc Selenide The top segments in the n-type semiconductor material market will be: • Silicon will reach $23.99 billion by 2030. • Gallium Arsenide will reach $8.72 billion by 2030. • Silicon Carbide will reach $6.91 billion by 2030. • Germanium will reach $4.51 billion by 2030. • Other Material Types will reach $4.07 billion by 2030.What Is The Driver Of The N-type Semiconductor Material Market?
The increased production of photovoltaic cells fueled the growth of the N-type semiconductor material market during the historic period. Photovoltaic cells refer to semiconductor devices that convert sunlight directly into electricity by generating an electric current when exposed to light. Production of photovoltaic cells increased as falling manufacturing costs made solar power more affordable and encouraged wider adoption worldwide. N-type semiconductor material enhances photovoltaic cells by providing higher efficiency, faster electron movement, and stronger resistance to impurities, helping the cells produce more consistent power. For instance, in August 2024, according to the Engelhart, a UK-based international commodity trading company, the world deployed 447 gigawatts of new solar photovoltaic capacity in 2023, marking an 87 percent increase from 2022 and accounting for 78 percent of all new renewable capacity added globally during the year. Therefore, the increased production of photovoltaic cells fueled the growth of the N-type semiconductor material industry.
Infographic Chart Showing Key Market Drivers Analysis And Restraints For N-Type Semiconductor Material Market
The chart presents an impact analysis of key drivers and restraints, quantifying their relative influence on the market's growth rate and helping assess the balance between growth enablers and limiting factors. This chart offers a high-level perspective; the full report contains more detailed insights.
How Will The Drivers Impact Growth In The Global N-type Semiconductor Material Market?
• Increasing Adoption Of Electric Vehicles (High) – During the forecast period, the increasing adoption of electric vehicles is expected to become a key growth driver for the n -type semiconductor material market by 2030. N -type materials such as silicon carbide (sic) and gallium nitride (gan) provide faster switching capability, improved energy efficiency, and superior thermal stability, making them essential for ev powertrains, inverters, and high -speed charging infrastructure. As global ev production continues to rise and governments strengthen policies supporting clean mobility, manufacturers are increasingly investing in n -type power devices to improve battery performance and extend vehicle range. This expanding integration of n -type semiconductors in automotive electronics is accelerating technological innovation and strengthening revenue growth across the semiconductor value chain. • Rising Need For Energy-Efficient Power Devices (High) – During the forecast period, the rising need for energy-efficient power devices is expected to emerge as a major factor driving the expansion of the n-type semiconductor material market by 2030. Increasing emphasis on energy efficiency across industries is driving strong demand for advanced semiconductor materials that support optimized power management. N-type materials such as silicon carbide (sic), gallium nitride (gan), and phosphorus-doped silicon enable highly efficient power conversion while minimizing heat generation and energy losses in electronic systems. These materials are increasingly utilized in renewable energy inverters, power supply units, and industrial automation equipment where efficient energy utilization is essential. As sustainability initiatives intensify and global energy regulations become more stringent, demand for high-efficiency n-type semiconductor materials continues to rise, enabling the development of advanced power management and energy control technologies across multiple sectors. • Growing Demand For High-Performance Microcontrollers (Low) – During the forecast period, the growing demand for high-performance microcontrollers is expected to act as a key growth catalyst for the n-type semiconductor material market by 2030. The increasing need for faster and more reliable electronic processing systems is driving demand for advanced semiconductor materials used in high-performance microcontrollers. N-type materials such as doped silicon, gallium arsenide (gaas), and indium phosphide (inp) offer high electron mobility and improved conductivity, enabling rapid signal processing and enhanced energy efficiency in microcontroller designs. These materials play a crucial role in applications including automotive electronics, industrial automation, internet of things (iot) devices, and smart consumer electronics. As industries continue to adopt intelligent, connected technologies, the requirement for high-performance and low-latency microcontrollers is expanding, thereby strengthening demand for n-type semiconductor materials.How Will The Restraints Impact Growth In The Global N-type Semiconductor Material Market?
• High Production Costs And Manufacturing Complexity (High) – During the forecast period, the high production costs and manufacturing complexity act as significant restraints for the n-type semiconductor material market, limiting large-scale adoption and profitability. The fabrication of advanced materials such as silicon carbide (sic), gallium nitride (gan), and indium phosphide (inp) requires highly controlled environments, specialized equipment, and precise doping techniques, all of which increase production expenses. Maintaining material purity and consistency adds further cost pressure, particularly for next-generation high-performance applications. Smaller manufacturers often face barriers to entry due to the capital-intensive nature of semiconductor fabrication and the need for continuous r&d investment. Overall, the high cost of production and process complexity constrain market scalability and delay broader commercialization of n-type semiconductor materials. • Supply Chain Disruptions And Raw Material Scarcity (High) – During the forecast period, the supply chain disruptions and raw material scarcity act as major restraints for the n-type semiconductor material market, affecting the availability and cost stability of key inputs. The production of n-type materials depends heavily on high-purity elements such as silicon, arsenic, phosphorus, and antimony, which are sourced from limited global suppliers. Geopolitical tensions, trade restrictions, and transportation bottlenecks can lead to supply delays and price fluctuations, disrupting manufacturing schedules. In addition, the semiconductor industry’s dependence on specialized chemicals and wafers amplifies vulnerability during periods of global shortages or export bans. Overall, supply chain fragility and raw material constraints hinder consistent production, elevate procurement costs, and pose significant challenges to market growth and resilience. • Stringent Quality Control And Purity Requirements (Medium) – During the forecast period, the the n-type semiconductor materials must meet extremely high purity and performance standards to ensure reliable functionality in electronic and photovoltaic applications. Even minor material defects or impurities can significantly affect device efficiency and yield rates. Manufacturers must invest heavily in advanced testing, monitoring, and quality assurance processes. These stringent requirements increase production complexity and operational costs throughout the value chain.Key Players In The Global N-type Semiconductor Material Market
Major companies operating in the n-type semiconductor material market are Shin-Etsu Chemical Co. Ltd., SUMCO Corporation, Siltronic AG, ShanghAI Wafer Works Co. Ltd., Okmetic Oyj, LONGi Green Energy Technology Co. Ltd., TCL Zhonghuan Renewable Energy Technology Co. Ltd., Wacker Chemie AG, OCI Company Ltd., Daqo New Energy Corp., GCL Technology Holdings Limited, Coherent Inc., Zhejiang Jinko Solar Co. Ltd., American Elements, Xiamen Powerway Advanced Material Co. Ltd., Wolfspeed Inc., SEG Solar Inc., Mitsubishi Materials Corporation, SiCrystal GmbH, ShanghAI Simgui Technology Co. Ltd., MSE Supplies LLC, Silicon Valley Microelectronics (SVM), UniversityWafer Inc., Virginia Semiconductor Inc., and Ocean Solar Co. Ltd.
This chart is for illustrative purposes; the full report includes a detailed competitor analysis and comprehensive overview of the top 10 companies in the market.

This chart maps companies by product innovation and brand strength, with bubble size indicating relative revenue, helping identify market leaders, challengers, and niche players. This is an illustrative chart; the full report provides a complete and accurate competitive analysis.
Global N-type Semiconductor Material Market Trends and Insights
Major companies operating in the N-type semiconductor material market are focusing on developing innovative solutions, such as N-type high-efficiency solar modules, to enhance power conversion efficiency, reduce energy losses, and meet the growing global demand for advanced photovoltaic technologies. N-type high-efficiency solar modules refer to advanced solar panels made from N-type semiconductor materials that offer superior energy conversion efficiency, better temperature tolerance, and longer operational lifespans than conventional P-type modules. For instance, in May 2025, Gstar Subic, a Singapore-based company that manufactures solar photovoltaic (PV) panels and cells, launched its first N-type high-efficiency solar module, at its production facility in the Philippines. The module features 183.75mm N-type cells arranged in a 72-cell bifacial dual-glass design, delivering a peak output of 595W with a conversion efficiency of 23.03%. It incorporates advanced technologies such as laser non-destructive scribing, super multi-busbar (SMBB) design, and high-density encapsulation, which enhance performance in low-light and high-temperature conditions.What Are Latest Mergers And Acquisitions In The N-type Semiconductor Material Market?
In December 2024, onsemi Corporation, a U.S.-based provider of intelligent power and sensing technologies, acquired Qorvo’s Silicon Carbide JFET technology business, including United Silicon Carbide, Inc., for an undisclosed amount. The acquisition aims to expand onsemi Corporation’s SiC portfolio, strengthen its power semiconductor capabilities, and meet growing demand for energy-efficient solutions in AI data centers and electric vehicles. Qorvo’s SiC JFET business is a US-based provider of advanced silicon carbide power devices for industrial, automotive, and data center applications offers high-performance silicon carbide (SiC) normally-on JFET transistors, which are N-type semiconductor devices.
Regional Outlook
Asia-Pacific was the largest region in the N-type semiconductor material market in 2025. North America is expected to be the fastest-growing region in the forecast period. The regions covered in this market report are Asia-Pacific, South East Asia, Western Europe, Eastern Europe, North America, South America, Middle East, Africa. The countries covered in this market report are Australia, Brazil, China, France, Germany, India, Indonesia, Japan, Taiwan, Russia, South Korea, UK, USA, Canada, Italy, Spain.What Defines the N-type Semiconductor Material Market?
The N-type semiconductor material market consists of sales of indium phosphide, cadmium telluride, antimony-doped materials, phosphorus-doped materials, arsenic-doped materials, and other semiconductor materials. Values in this market are ‘factory gate’ values, that is, the value of goods sold by the manufacturers or creators of the goods, whether to other entities (including downstream manufacturers, wholesalers, distributors, and retailers) or directly to end customers. The value of goods in this market includes related services sold by the creators of the goods.How is Market Value Defined and Measured?
The market value is defined as the revenues that enterprises gain from the sale of goods and/or services within the specified market and geography through sales, grants, or donations in terms of the currency (in USD unless otherwise specified). The revenues for a specified geography are consumption values that are revenues generated by organizations in the specified geography within the market, irrespective of where they are produced. It does not include revenues from resales along the supply chain, either further along the supply chain or as part of other products.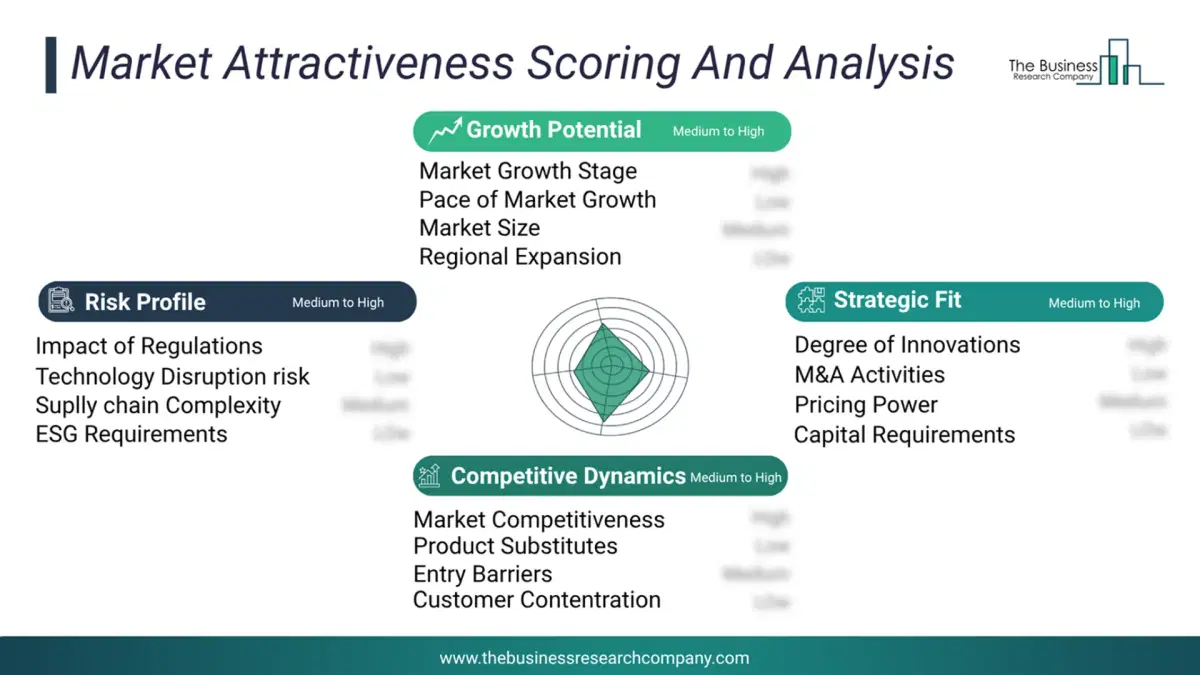
This chart presents market attractiveness based on a quantitative evaluation of growth, competition, strategic alignment, and risk, offering a clear view of opportunity areas for decision-making. This chart is for illustrative purposes; the full report contains the complete analysis.
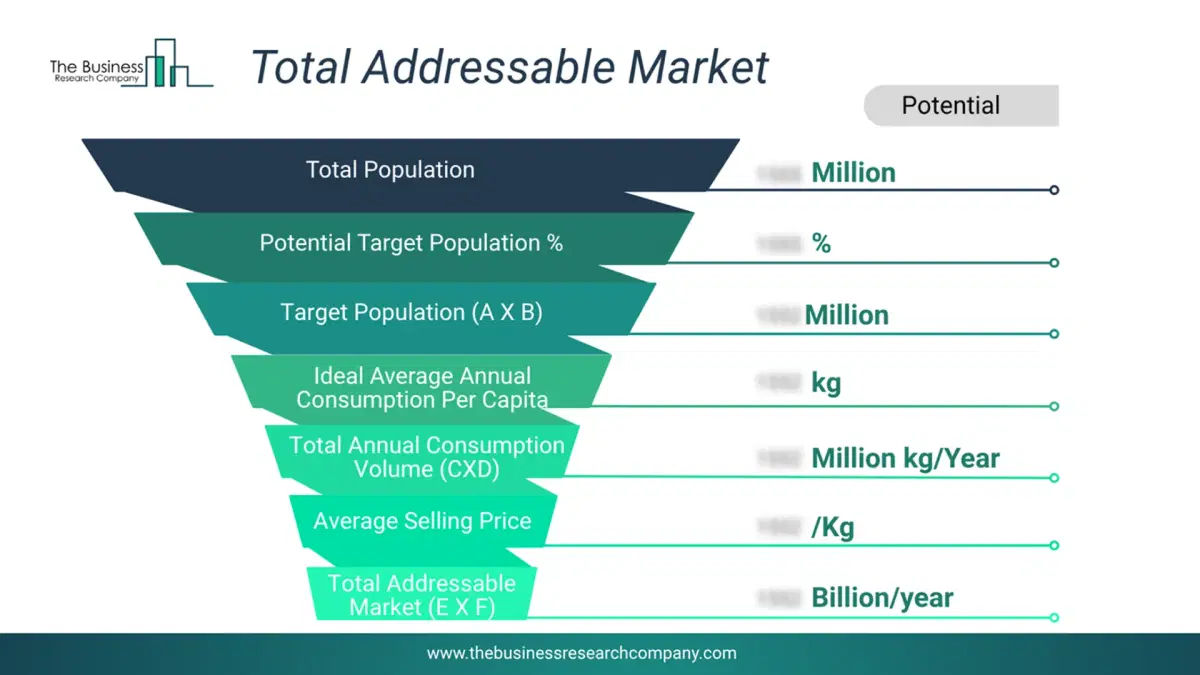
This chart highlights the Total Addressable Market (TAM) by estimating the maximum revenue opportunity using an assumption-driven approach, supporting strategic planning and opportunity sizing across markets. The chart is illustrative; the full report provides a more comprehensive analysis.
What Key Data and Analysis Are Included in the N-type Semiconductor Material Market Report 2026?
The n-type semiconductor material market research report is one of a series of new reports from The Business Research Company that provides market statistics, including industry global market size, regional shares, competitors with the market share, detailed market segments, market trends and opportunities, and any further data you may need to thrive in the n-type semiconductor material industry. The market research report delivers a complete perspective of everything you need, with an in-depth analysis of the current and future state of the industry.N-type Semiconductor Material Market Report 2026 Market Report Forecast Analysis
| Report Attribute | Details |
|---|---|
| Market Size Value In 2026 | $37.21 billion |
| Revenue Forecast In 2030 | $47.91 billion |
| Growth Rate | CAGR of 6.5% from 2026 to 2030 |
| Base Year For Estimation | 2025 |
| Actual Estimates/Historical Data | 2020-2025 |
| Forecast Period | 2026 - 2030 |
| Market Representation | Revenue in USD Billion and CAGR from 2026 to 2030 |
| Segments Covered | Material Type, Device Type, Doping Material, Application |
| Regional Scope | Asia-Pacific, Western Europe, Eastern Europe, North America, South America, Middle East, Africa |
| Country Scope | The countries covered in the report are Australia, Brazil, China, France, Germany, India, ... |
| Key Companies Profiled | Shin-Etsu Chemical Co. Ltd., SUMCO Corporation, Siltronic AG, ShanghAI Wafer Works Co. Ltd., Okmetic Oyj, LONGi Green Energy Technology Co. Ltd., TCL Zhonghuan Renewable Energy Technology Co. Ltd., Wacker Chemie AG, OCI Company Ltd., Daqo New Energy Corp., GCL Technology Holdings Limited, Coherent Inc., Zhejiang Jinko Solar Co. Ltd., American Elements, Xiamen Powerway Advanced Material Co. Ltd., Wolfspeed Inc., SEG Solar Inc., Mitsubishi Materials Corporation, SiCrystal GmbH, ShanghAI Simgui Technology Co. Ltd., MSE Supplies LLC, Silicon Valley Microelectronics (SVM), UniversityWafer Inc., Virginia Semiconductor Inc., and Ocean Solar Co. Ltd. </b> |
| Customization Scope | Request for Customization |
| Pricing And Purchase Options | Explore Purchase Options |